A new chief financial officer is stepping into one of the most demanding finance roles in Nordic infrastructure.
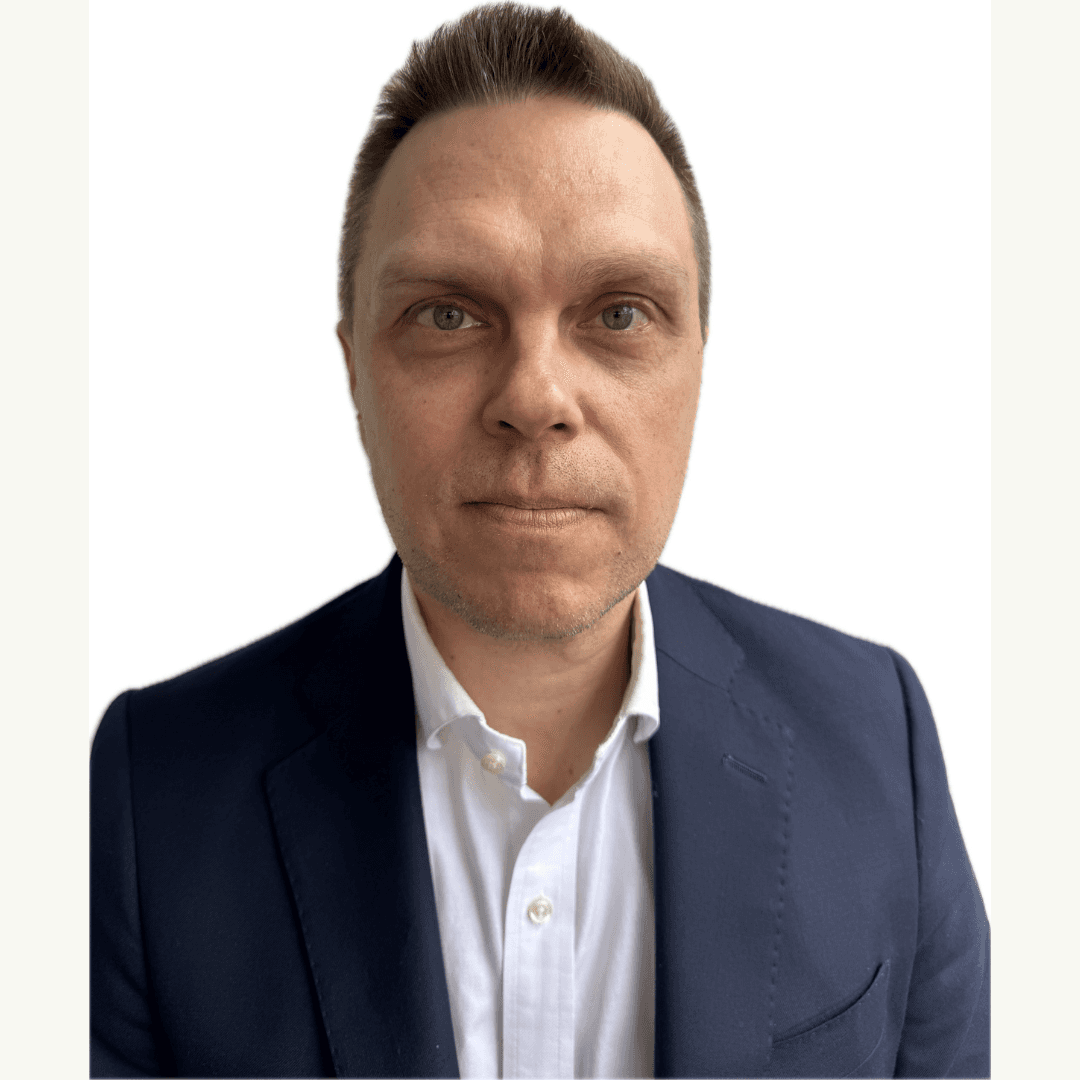
GRK Infra announced recently that Perttu Piilo will become CFO and a member of the group management team from July 1, succeeding Markku Puolanne after a transition period.
Piilo arrives as GRK moves through its most expansionary phase since listing: a record order backlog, a major acquisition, larger infrastructure contracts in Sweden and Finland, and a broader push beyond its traditional public sector base.
The appointment looks less like routine succession planning and more like preparation for a more financially complex company.
A CFO hire aligned with the next phase
Piilo joins from Fira Oy, where he served as CFO. Earlier finance leadership roles at Nordic Waterproofing AB and Aro Systems Oy gave him experience in construction and telecommunications, sectors where project execution, capital allocation, and working capital discipline tend to matter more than headline growth alone.
CEO Mika Mäenpää framed the hire explicitly around GRK’s expansion plans.
“I am pleased to welcome Perttu to GRK at this strategically important stage, as the company is transitioning into the next development phase and seeking growth both organically and through acquisitions. Perttu's strong experience in financial management excellently supports the implementation of GRK's strategy.”
That strategy is becoming clearer. GRK is no longer operating purely as a Nordic infrastructure contractor competing for domestic public projects. It is building a broader infrastructure platform with greater exposure to energy, industrial construction, rail, and data center related work across multiple countries.
The outgoing CFO leaves behind a different company
Puolanne departs after overseeing GRK’s transition into listed company life and a period of rapid growth. During his tenure, the company expanded revenue to EUR 872.3 million in 2025, up 20% year over year, while building a significantly larger project pipeline.
Mäenpää acknowledged that transformation in the announcement.
“At the same time, I would like to thank Markku for his important role at GRK during these significant years. We have grown rapidly, started a new phase as a listed company and made determined progress towards our strategic goals. We wish Markku all the best in the future.”
Puolanne’s departure coincides with what is likely the most operationally demanding financial transition in the company’s history. His successor inherits not a stabilization brief, but an integration and scaling challenge.
The acquisition that explains the timing
The clearest signal came four days before the CFO announcement.
On May 18, GRK signed an agreement to acquire Keski-Suomen Betonirakenne Oy and its subsidiaries in a transaction valued at up to EUR 97.55 million including earn-outs. The structure includes roughly EUR 58.7 million in cash and 1.67 million new GRK shares valued at EUR 16 each.
KSBR generated EUR 124 million in revenue and EUR 10.9 million in operating profit in 2025, while growing revenue by 63% year over year. Its year-end order book stood at EUR 110.3 million.
The acquisition is expected to close on July 1, the same day Piilo officially assumes the CFO role.
That alignment is unlikely to be accidental.
The deal materially changes GRK’s financial profile. It expands the company deeper into concrete structures, energy infrastructure, industrial projects, and data center construction. It also broadens the customer mix toward private sector clients, reducing reliance on public procurement cycles that have historically shaped Nordic infrastructure contractors.
More importantly, it increases financial complexity immediately. Integration costs, acquisition financing, working capital requirements, and multi-year earn-out obligations now sit alongside a rapidly expanding project portfolio.
A larger Nordic infrastructure platform is emerging
GRK’s recent contract wins suggest the company is positioning itself for larger and longer-duration projects across the Nordics.
In Finland, the company was selected for the first phase of the Turku Tramway Alliance project. GRK’s share of the initial phase is estimated at roughly EUR 12 million, but the full project could eventually reach approximately EUR 190 million for the company if later phases proceed as expected.
In Sweden, GRK secured a SEK 595 million rail bridge infrastructure contract linked to the Norrbotniabanan railway project. Management described the award as another step in strengthening the company’s Swedish growth platform.
The strategic direction is becoming easier to read. GRK is concentrating on infrastructure segments tied to long-cycle public investment and the green transition: rail, energy, electrification, industrial infrastructure, and urban transport.
The KSBR acquisition accelerates that positioning rather than changing it.
The financial backdrop is more nuanced than the backlog suggests
At first glance, GRK’s first-quarter numbers looked weaker. Revenue fell 36% year over year to EUR 111.9 million after several large projects completed during 2025.
But the underlying picture was stronger than the top line implied.
Adjusted operating margin improved to 5.3% from 5.0%, while EBITDA margin rose to 9.4% from 6.8%. The equity ratio strengthened to 54.2%. Meanwhile, the order backlog reached a record EUR 883.1 million.
Once KSBR’s EUR 110.3 million backlog is added, GRK will likely be operating with the largest project pipeline in its history as a listed company. That creates opportunity and pressure at the same time.
Large infrastructure groups rarely struggle because demand disappears. They struggle when growth outpaces operational control, integration discipline, or balance sheet capacity. GRK’s leadership changes suggest the company understands that the next phase depends as much on financial execution as on winning contracts.
Piilo is stepping into the role at precisely that moment.
·
5 min read
Explore and follow profiles from this article to get timely updates:
A new chief financial officer is stepping into one of the most demanding finance roles in Nordic infrastructure.
GRK Infra announced recently that Perttu Piilo will become CFO and a member of the group management team from July 1, succeeding Markku Puolanne after a transition period.
Piilo arrives as GRK moves through its most expansionary phase since listing: a record order backlog, a major acquisition, larger infrastructure contracts in Sweden and Finland, and a broader push beyond its traditional public sector base.
The appointment looks less like routine succession planning and more like preparation for a more financially complex company.
A CFO hire aligned with the next phase
Piilo joins from Fira Oy, where he served as CFO. Earlier finance leadership roles at Nordic Waterproofing AB and Aro Systems Oy gave him experience in construction and telecommunications, sectors where project execution, capital allocation, and working capital discipline tend to matter more than headline growth alone.
CEO Mika Mäenpää framed the hire explicitly around GRK’s expansion plans.
“I am pleased to welcome Perttu to GRK at this strategically important stage, as the company is transitioning into the next development phase and seeking growth both organically and through acquisitions. Perttu's strong experience in financial management excellently supports the implementation of GRK's strategy.”
That strategy is becoming clearer. GRK is no longer operating purely as a Nordic infrastructure contractor competing for domestic public projects. It is building a broader infrastructure platform with greater exposure to energy, industrial construction, rail, and data center related work across multiple countries.
The outgoing CFO leaves behind a different company
Puolanne departs after overseeing GRK’s transition into listed company life and a period of rapid growth. During his tenure, the company expanded revenue to EUR 872.3 million in 2025, up 20% year over year, while building a significantly larger project pipeline.
Mäenpää acknowledged that transformation in the announcement.
“At the same time, I would like to thank Markku for his important role at GRK during these significant years. We have grown rapidly, started a new phase as a listed company and made determined progress towards our strategic goals. We wish Markku all the best in the future.”
Puolanne’s departure coincides with what is likely the most operationally demanding financial transition in the company’s history. His successor inherits not a stabilization brief, but an integration and scaling challenge.
The acquisition that explains the timing
The clearest signal came four days before the CFO announcement.
On May 18, GRK signed an agreement to acquire Keski-Suomen Betonirakenne Oy and its subsidiaries in a transaction valued at up to EUR 97.55 million including earn-outs. The structure includes roughly EUR 58.7 million in cash and 1.67 million new GRK shares valued at EUR 16 each.
KSBR generated EUR 124 million in revenue and EUR 10.9 million in operating profit in 2025, while growing revenue by 63% year over year. Its year-end order book stood at EUR 110.3 million.
The acquisition is expected to close on July 1, the same day Piilo officially assumes the CFO role.
That alignment is unlikely to be accidental.
The deal materially changes GRK’s financial profile. It expands the company deeper into concrete structures, energy infrastructure, industrial projects, and data center construction. It also broadens the customer mix toward private sector clients, reducing reliance on public procurement cycles that have historically shaped Nordic infrastructure contractors.
More importantly, it increases financial complexity immediately. Integration costs, acquisition financing, working capital requirements, and multi-year earn-out obligations now sit alongside a rapidly expanding project portfolio.
A larger Nordic infrastructure platform is emerging
GRK’s recent contract wins suggest the company is positioning itself for larger and longer-duration projects across the Nordics.
In Finland, the company was selected for the first phase of the Turku Tramway Alliance project. GRK’s share of the initial phase is estimated at roughly EUR 12 million, but the full project could eventually reach approximately EUR 190 million for the company if later phases proceed as expected.
In Sweden, GRK secured a SEK 595 million rail bridge infrastructure contract linked to the Norrbotniabanan railway project. Management described the award as another step in strengthening the company’s Swedish growth platform.
The strategic direction is becoming easier to read. GRK is concentrating on infrastructure segments tied to long-cycle public investment and the green transition: rail, energy, electrification, industrial infrastructure, and urban transport.
The KSBR acquisition accelerates that positioning rather than changing it.
The financial backdrop is more nuanced than the backlog suggests
At first glance, GRK’s first-quarter numbers looked weaker. Revenue fell 36% year over year to EUR 111.9 million after several large projects completed during 2025.
But the underlying picture was stronger than the top line implied.
Adjusted operating margin improved to 5.3% from 5.0%, while EBITDA margin rose to 9.4% from 6.8%. The equity ratio strengthened to 54.2%. Meanwhile, the order backlog reached a record EUR 883.1 million.
Once KSBR’s EUR 110.3 million backlog is added, GRK will likely be operating with the largest project pipeline in its history as a listed company. That creates opportunity and pressure at the same time.
Large infrastructure groups rarely struggle because demand disappears. They struggle when growth outpaces operational control, integration discipline, or balance sheet capacity. GRK’s leadership changes suggest the company understands that the next phase depends as much on financial execution as on winning contracts.
Piilo is stepping into the role at precisely that moment.
Follow moves like this on the Listeds Executive Intelligence Platform.
Investor Event
Listeds Investor Event · Defence
Nordic defence is in a once-in-a-generation growth cycle. Eight listed and pre-IPO companies pitch to 100+ invited investors at Valkoinen Sali, Helsinki
21 September 2026

Latest on Listeds

