China is often framed in Nordic boardrooms as a risk to be managed rather than a system to learn from. Juha Luhtanen, CEO of the Finnish sportswear and fashion group Luhta, takes a different view. After two decades of Luhta operations in the country, he sees a market shaped by long-term partnerships, industrial innovation, and rapid capital deployment, not a low-value “developing” economy.
The decisive factor to manufacturing success in China, Luhtanen argues, is something that budget-driven decision making often overlooks. “It is still strongly a relationship-based business, even today.” That logic has guided Luhta’s expansion east over the past two decades, supported by technological progress and resilient even as labor costs have risen.
Founded in 1907, Luhta remains a 100 percent family-owned company. From its roots in Lahti, it has grown into an international group whose brands, such as Luhta, Icepeak, Rukka, and Dachstein, span outdoor wear, sportswear, fashion, footwear, and home textiles. Today, Luhta’s products are sold through more than 7,000 sales sites and its own retail network of 52 stores. Operationally, however, the center of gravity has shifted east.
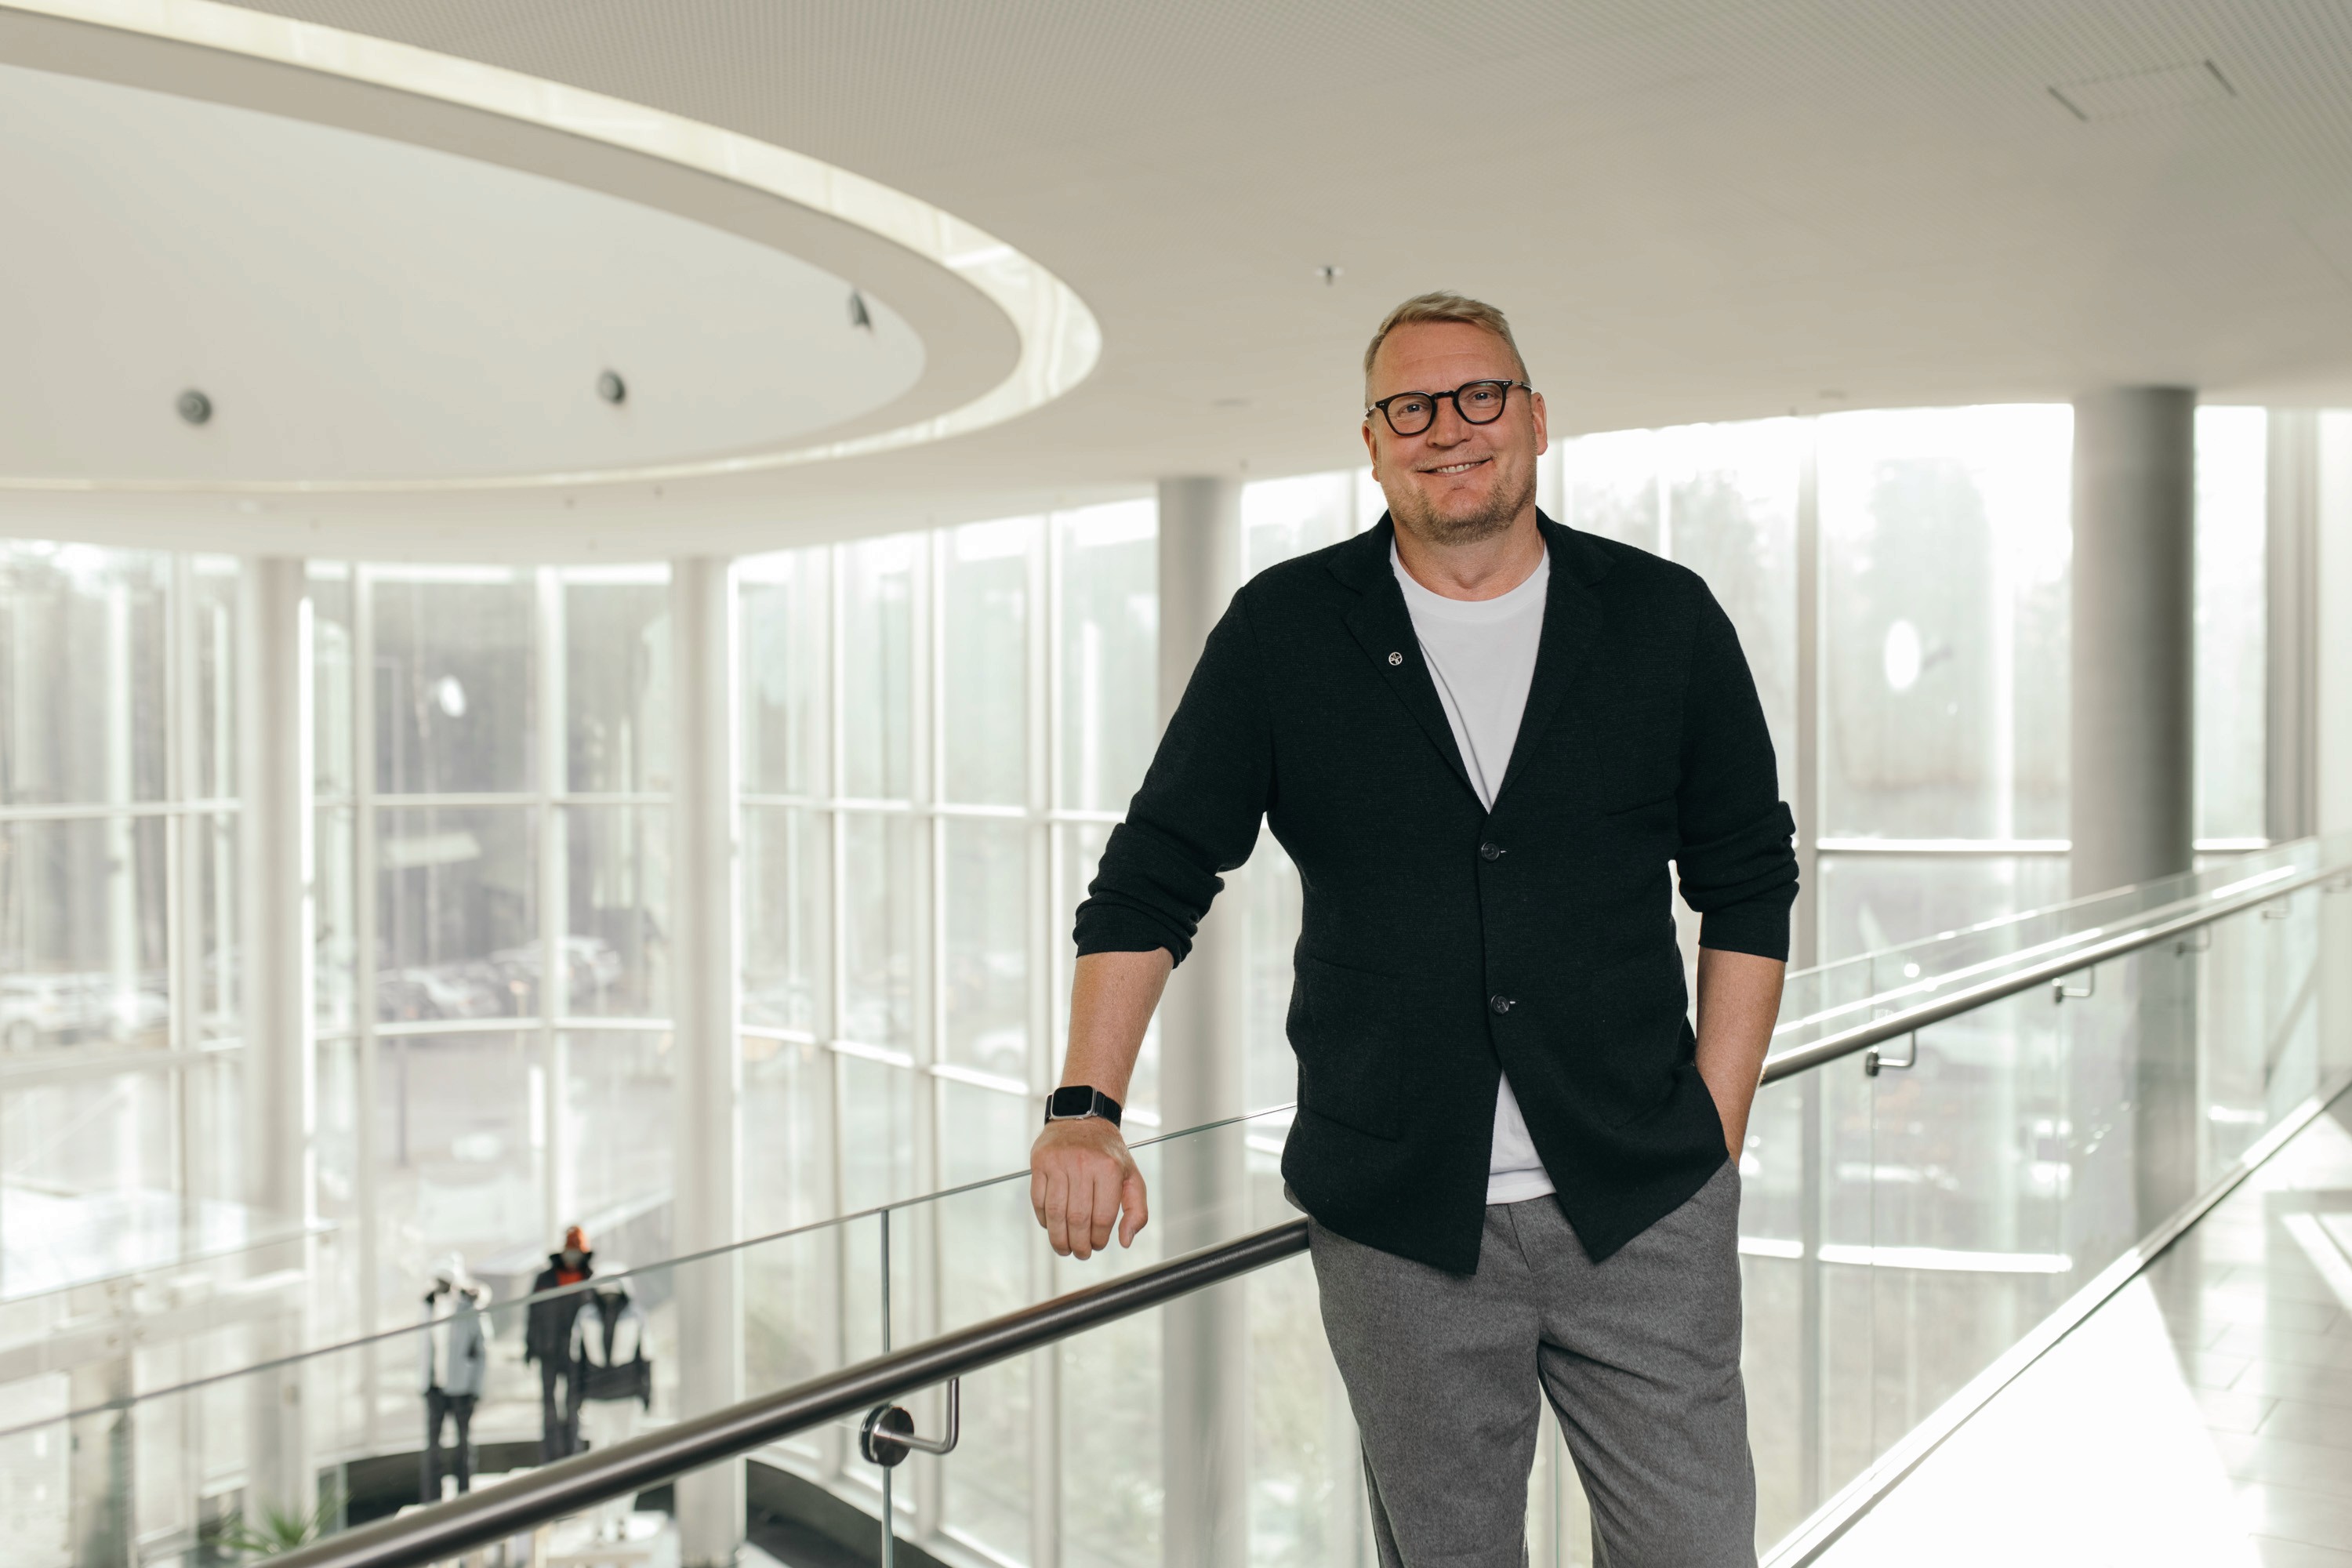
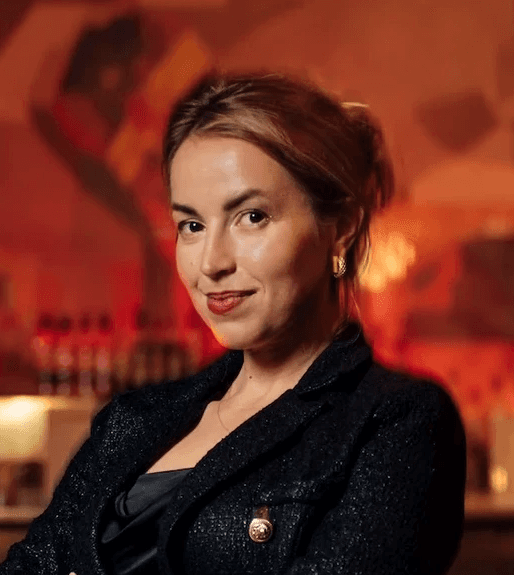
Juha Luhtanen has spent most of his career at Luhta, beginning as a product manager in the 1990s and later taking on roles in branding and sales. Before becoming CEO in 2021, he served as deputy managing director.
Luhtanen’s own career reflects that long-term mindset. He joined Luhta nearly three decades ago as a product manager and has grown with the company through multiple roles, spanning product development, production, sourcing, and global sales, before becoming CEO. The experience has given him an unusually deep understanding of how strategic decisions ripple through the organization, from factory floors to retail shelves.
Luhta now manufactures roughly 90 percent of its products in China, supported by its own local organization and a network of long-term partners. This is not unusual since many Finnish apparel makers have shifted most of their production abroad, including Marimekko. Lower production costs play a strong role, Luhtanen acknowledges, but he insists they are not the only decisive factor. What ultimately determines success, he says, is leadership behavior, long-term commitment, and how trust is built over time.
Relationships are built with time, not contracts
Luhtanen is clear about what actually makes Chinese manufacturing work. “What we have learned is that the longer the relationship, the easier and more trustworthy it is.”
Over the years, Luhta has experimented with short-term sourcing and new factory relationships. The result was consistent. When challenges arise, whether related to quality, delays, or last-minute changes, long-term partners respond differently.
“When you have long-term partners, they can solve many challenges in the supply chain much more easily. The commitment is much stronger.”
Those relationships are rarely built in meeting rooms. “In Chinese culture, relationships are built over dinners and spending time. It is not only about the business. It is also about the personal relationships.”
For Finnish leaders used to directness and efficiency, this requires adjustment. “It does not come naturally to us because we are very straightforward. Trust comes bit by bit, and it takes patience.”
Luhtanen adds that this logic is not unique to China but applies across much of Asia.
Innovation no longer follows Western assumptions
One of the most underestimated shifts, Luhtanen argues, is how rapidly the world’s second-largest economy has evolved. “China has changed so much in the past 10 years that it’s a totally different country from what it was 20 years ago.”
In the apparel industry, China has moved decisively beyond execution. “They have taken the driver’s seat in design, technical solutions, and sustainability.” For example, Shenzhou International, a key supplier to global brands such as Nike and Adidas, is investing heavily in intelligent garment factories that use automated sewing lines, AI-based quality inspection, and real-time production data, according to Chinese industry reporting.
The innovation cycle itself also looks different in Finland. When strategic priorities are set in China, capital and resources tend to follow quickly. “When decisions are made to invest in innovation, the funding is much easier to acquire.” Part of that momentum comes from strong central government planning, implemented through programs such as the Textile Industry Quality Upgrade Implementation Plan (2023–2025), which channels funding toward automation, digital manufacturing, and higher-value textile innovation.
By contrast, Nordic companies often face longer and more fragmented paths to similar support. “In Finland, the support to make these investments is more difficult to get.”
Another misconception Luhtanen challenges is the idea of China as a low-wage manufacturing base. “The misconception is coming from history,” he says. Today, the bigger issue is not cost but labor availability. “The challenge today is actually to get workers into the factories,” he notes, as younger generations turn away from manual work, forcing manufacturers to raise wages and rethink how production is organized.
Against that backdrop, Luhtanen sees another structural shift approaching quickly. “I believe 100 percent that fully automated production will happen sooner than later.”
Standardized sewing is already being handled by machines. “It is only a question of time before they can do more complicated seams and cuts.”
This will fundamentally reshape how and where clothing is made, including in China.
Why Luhta remains small in the Chinese consumer market
Despite its deep manufacturing presence, Luhta’s consumer business in China remains modest. This stands in contrast to companies such as Amer Sports, whose brands Arc’teryx and Salomon, now owned by China’s Anta Sports, have been expanding rapidly in the Chinese market, reporting double-digit sales growth in the third quarter. The comparison naturally raises the question: what would it take for Luhta to make it big in China?
“We sell a couple of million euros in China, which from a China perspective is nothing,” Luhtanen says. “To be relevant, you would need a couple of zeros more.” The scale gap is underscored by Luhta’s 2024 annual report, which shows total group revenue of EUR 190.2 million.
Luhta entered Chinese retail in 2010 and, at its peak, operated close to 90 stores. Moving beyond that level, however, would require a fundamentally different operating model. China is a fully vertical market, where consumer demand drives decisions almost in real time.
“The consumers drive the business, not the wholesale buyers,” Luhtanen notes, adding that Luhta is still, at its core, a wholesale-driven company.
The pace of decision-making illustrates the gap. Product cycles in China are dramatically shorter than in Europe. “Right now, we are designing the collection for the Chinese market for autumn-winter 26. In Europe, those decisions were made a year and a half ago.”
Scaling up would also mean committing to vastly larger volumes and sharper localization. “You need production runs in hundreds of thousands per style, with different sizing, different fits, and huge marketing investments.”
For Luhtanen, this assessment reflects realism rather than reluctance. “It requires a lot of capital and risk-taking. It is a very tough market.”
Ownership adds another constraint. Luhtanen does not see Luhta being sold to a foreign owner anytime soon. The company’s structure is complex, its ownership is firmly family-based, and much of its business remains centered in Europe and in fragmented category markets. Brands such as Icepeak, for example, are highly successful in specific segments, including alpine skiing and outdoor, but the approach is wholesale customer brand-driven rather than consumer brand-driven.
“We would need to improve our brands’ consumer recognition significantly for any Chinese company to be interested in our brands,” Luhtanen says.
For now, Luhtanen is careful not to overstate what comes next. While Luhta’s presence in the Chinese consumer market remains limited, he is clear that the potential is there. Recent market developments, he says, are moving in a direction that could create room for a more measured expansion. The question, in his view, is less about ambition than timing. The details, he hints, are better saved for another conversation, one that may not be too far off.
Presence and ownership change everything
Luhtanen travels to China regularly, often several times a year, and sees physical presence as non-negotiable. “You cannot manage China operations from Europe,” he says, praising the long-term China operations management and the local team.
Luhta operates through a wholly owned subsidiary in Suzhou, established in 2006, with more than 300 employees, continuing seamlessly the processes started in Finland by Brand and Design teams. The China operations include R&D, sourcing, quality control, and extensive logistics operations. “We wanted to work in China as a Chinese company, with our own factory and partner factories working closely together with all of our other functions, whether in Finland or in China.”
That structure proved decisive during the Covid-19 pandemic. “When Europe was closed, China was open, and vice versa. We were able to balance the situation because we had our own operation there.”
That operational setup has continued to pay off. China remains central to Luhta’s cost structure and delivery reliability at a time when logistics volatility still challenges European brands. Despite container shortages and longer transit times during 2024, Luhta maintained a record gross margin of 51.7 percent, underscoring the resilience of its sourcing model.
Luhtanen credits long-term local employees as one of Luhta’s most important assets. “Without those people who understood our vision and could bridge the cultures, we would not have succeeded.”
The lesson most executives miss
For Luhtanen, the hardest part of leadership today is not understanding China, but resisting the urge to overmanage. Having worked across many of the roles he now oversees, he often sees the downstream impact of decisions immediately.
“The hardest part is not to micromanage,” he says. That discipline mirrors the demands of operating across systems that move at different speeds and follow different logics. China, in his experience, rewards leaders who can balance decisiveness with restraint, presence with autonomy, and long-term intent inside fast-moving markets.
After nearly 30 years at the same company, Luhtanen’s conclusion is less about geography than governance. In complex environments, success is rarely driven by optimization alone. It depends on whether leaders are willing to invest time, accept ambiguity, and allow organizations to grow into the responsibilities they are given.
Those who fail to do so, he suggests, risk misunderstanding not only China, but leadership itself.
·
5 min read
China is often framed in Nordic boardrooms as a risk to be managed rather than a system to learn from. Juha Luhtanen, CEO of the Finnish sportswear and fashion group Luhta, takes a different view. After two decades of Luhta operations in the country, he sees a market shaped by long-term partnerships, industrial innovation, and rapid capital deployment, not a low-value “developing” economy.
The decisive factor to manufacturing success in China, Luhtanen argues, is something that budget-driven decision making often overlooks. “It is still strongly a relationship-based business, even today.” That logic has guided Luhta’s expansion east over the past two decades, supported by technological progress and resilient even as labor costs have risen.
Founded in 1907, Luhta remains a 100 percent family-owned company. From its roots in Lahti, it has grown into an international group whose brands, such as Luhta, Icepeak, Rukka, and Dachstein, span outdoor wear, sportswear, fashion, footwear, and home textiles. Today, Luhta’s products are sold through more than 7,000 sales sites and its own retail network of 52 stores. Operationally, however, the center of gravity has shifted east.
Juha Luhtanen has spent most of his career at Luhta, beginning as a product manager in the 1990s and later taking on roles in branding and sales. Before becoming CEO in 2021, he served as deputy managing director.
Luhtanen’s own career reflects that long-term mindset. He joined Luhta nearly three decades ago as a product manager and has grown with the company through multiple roles, spanning product development, production, sourcing, and global sales, before becoming CEO. The experience has given him an unusually deep understanding of how strategic decisions ripple through the organization, from factory floors to retail shelves.
Luhta now manufactures roughly 90 percent of its products in China, supported by its own local organization and a network of long-term partners. This is not unusual since many Finnish apparel makers have shifted most of their production abroad, including Marimekko. Lower production costs play a strong role, Luhtanen acknowledges, but he insists they are not the only decisive factor. What ultimately determines success, he says, is leadership behavior, long-term commitment, and how trust is built over time.
Relationships are built with time, not contracts
Luhtanen is clear about what actually makes Chinese manufacturing work. “What we have learned is that the longer the relationship, the easier and more trustworthy it is.”
Over the years, Luhta has experimented with short-term sourcing and new factory relationships. The result was consistent. When challenges arise, whether related to quality, delays, or last-minute changes, long-term partners respond differently.
“When you have long-term partners, they can solve many challenges in the supply chain much more easily. The commitment is much stronger.”
Those relationships are rarely built in meeting rooms. “In Chinese culture, relationships are built over dinners and spending time. It is not only about the business. It is also about the personal relationships.”
For Finnish leaders used to directness and efficiency, this requires adjustment. “It does not come naturally to us because we are very straightforward. Trust comes bit by bit, and it takes patience.”
Luhtanen adds that this logic is not unique to China but applies across much of Asia.
Innovation no longer follows Western assumptions
One of the most underestimated shifts, Luhtanen argues, is how rapidly the world’s second-largest economy has evolved. “China has changed so much in the past 10 years that it’s a totally different country from what it was 20 years ago.”
In the apparel industry, China has moved decisively beyond execution. “They have taken the driver’s seat in design, technical solutions, and sustainability.” For example, Shenzhou International, a key supplier to global brands such as Nike and Adidas, is investing heavily in intelligent garment factories that use automated sewing lines, AI-based quality inspection, and real-time production data, according to Chinese industry reporting.
The innovation cycle itself also looks different in Finland. When strategic priorities are set in China, capital and resources tend to follow quickly. “When decisions are made to invest in innovation, the funding is much easier to acquire.” Part of that momentum comes from strong central government planning, implemented through programs such as the Textile Industry Quality Upgrade Implementation Plan (2023–2025), which channels funding toward automation, digital manufacturing, and higher-value textile innovation.
By contrast, Nordic companies often face longer and more fragmented paths to similar support. “In Finland, the support to make these investments is more difficult to get.”
Another misconception Luhtanen challenges is the idea of China as a low-wage manufacturing base. “The misconception is coming from history,” he says. Today, the bigger issue is not cost but labor availability. “The challenge today is actually to get workers into the factories,” he notes, as younger generations turn away from manual work, forcing manufacturers to raise wages and rethink how production is organized.
Against that backdrop, Luhtanen sees another structural shift approaching quickly. “I believe 100 percent that fully automated production will happen sooner than later.”
Standardized sewing is already being handled by machines. “It is only a question of time before they can do more complicated seams and cuts.”
This will fundamentally reshape how and where clothing is made, including in China.
Why Luhta remains small in the Chinese consumer market
Despite its deep manufacturing presence, Luhta’s consumer business in China remains modest. This stands in contrast to companies such as Amer Sports, whose brands Arc’teryx and Salomon, now owned by China’s Anta Sports, have been expanding rapidly in the Chinese market, reporting double-digit sales growth in the third quarter. The comparison naturally raises the question: what would it take for Luhta to make it big in China?
“We sell a couple of million euros in China, which from a China perspective is nothing,” Luhtanen says. “To be relevant, you would need a couple of zeros more.” The scale gap is underscored by Luhta’s 2024 annual report, which shows total group revenue of EUR 190.2 million.
Luhta entered Chinese retail in 2010 and, at its peak, operated close to 90 stores. Moving beyond that level, however, would require a fundamentally different operating model. China is a fully vertical market, where consumer demand drives decisions almost in real time.
“The consumers drive the business, not the wholesale buyers,” Luhtanen notes, adding that Luhta is still, at its core, a wholesale-driven company.
The pace of decision-making illustrates the gap. Product cycles in China are dramatically shorter than in Europe. “Right now, we are designing the collection for the Chinese market for autumn-winter 26. In Europe, those decisions were made a year and a half ago.”
Scaling up would also mean committing to vastly larger volumes and sharper localization. “You need production runs in hundreds of thousands per style, with different sizing, different fits, and huge marketing investments.”
For Luhtanen, this assessment reflects realism rather than reluctance. “It requires a lot of capital and risk-taking. It is a very tough market.”
Ownership adds another constraint. Luhtanen does not see Luhta being sold to a foreign owner anytime soon. The company’s structure is complex, its ownership is firmly family-based, and much of its business remains centered in Europe and in fragmented category markets. Brands such as Icepeak, for example, are highly successful in specific segments, including alpine skiing and outdoor, but the approach is wholesale customer brand-driven rather than consumer brand-driven.
“We would need to improve our brands’ consumer recognition significantly for any Chinese company to be interested in our brands,” Luhtanen says.
For now, Luhtanen is careful not to overstate what comes next. While Luhta’s presence in the Chinese consumer market remains limited, he is clear that the potential is there. Recent market developments, he says, are moving in a direction that could create room for a more measured expansion. The question, in his view, is less about ambition than timing. The details, he hints, are better saved for another conversation, one that may not be too far off.
Presence and ownership change everything
Luhtanen travels to China regularly, often several times a year, and sees physical presence as non-negotiable. “You cannot manage China operations from Europe,” he says, praising the long-term China operations management and the local team.
Luhta operates through a wholly owned subsidiary in Suzhou, established in 2006, with more than 300 employees, continuing seamlessly the processes started in Finland by Brand and Design teams. The China operations include R&D, sourcing, quality control, and extensive logistics operations. “We wanted to work in China as a Chinese company, with our own factory and partner factories working closely together with all of our other functions, whether in Finland or in China.”
That structure proved decisive during the Covid-19 pandemic. “When Europe was closed, China was open, and vice versa. We were able to balance the situation because we had our own operation there.”
That operational setup has continued to pay off. China remains central to Luhta’s cost structure and delivery reliability at a time when logistics volatility still challenges European brands. Despite container shortages and longer transit times during 2024, Luhta maintained a record gross margin of 51.7 percent, underscoring the resilience of its sourcing model.
Luhtanen credits long-term local employees as one of Luhta’s most important assets. “Without those people who understood our vision and could bridge the cultures, we would not have succeeded.”
The lesson most executives miss
For Luhtanen, the hardest part of leadership today is not understanding China, but resisting the urge to overmanage. Having worked across many of the roles he now oversees, he often sees the downstream impact of decisions immediately.
“The hardest part is not to micromanage,” he says. That discipline mirrors the demands of operating across systems that move at different speeds and follow different logics. China, in his experience, rewards leaders who can balance decisiveness with restraint, presence with autonomy, and long-term intent inside fast-moving markets.
After nearly 30 years at the same company, Luhtanen’s conclusion is less about geography than governance. In complex environments, success is rarely driven by optimization alone. It depends on whether leaders are willing to invest time, accept ambiguity, and allow organizations to grow into the responsibilities they are given.
Those who fail to do so, he suggests, risk misunderstanding not only China, but leadership itself.
Investor Event
Listeds Investor Event · Defence
Nordic defence is in a once-in-a-generation growth cycle. Eight listed and pre-IPO companies pitch to 100+ invited investors at Valkoinen Sali, Helsinki
21 September 2026

Latest on Listeds

