Weak consumer confidence has made First North small caps look cheap. Kai Tavakka of Accendo Capital argues the real constraint is ownership, not price. Small listed companies need committed, long-term owners who work with boards and management when the market is not paying attention.
First North has been a hard place to own. The Nasdaq First North Finland index is down about 29% over the past year and about 65% over the past five, as of 6 August 2026. For many investors, that is a reason to stay away. For Kai Tavakka, Managing Partner of the Nordic active-ownership investor Accendo Capital, it is closer to the opposite.
"The mistake is to read a falling small-cap index only as a verdict on the companies inside it," Tavakka says. "Often it is also a verdict on confidence, liquidity and who is willing to own these companies through the cycle."
Why the segment got cheaper
Accendo ties the sell-off to consumer confidence. Appetite for smaller, higher-risk listed companies tends to follow it, and on Accendo’s reading confidence in Finland and Sweden has stayed weak since 2021. When households feel poorer and investors become more cautious, money moves toward larger, more familiar names. In a retail-driven market, the buyers for small and micro caps can disappear quickly.
“That pulls valuations down across the small-cap segment,” Tavakka says, “even when the potential of selected companies has not deteriorated in the same way.”
The result, on Accendo's reading, is a market where price can detach from quality. Tavakka points to a sharp compression in valuation multiples over the past five years, even as many underlying companies have improved their products, technology and cost structures.
"Of course, several companies have not delivered on their original growth ambitions," he says. "But in selected cases, we see the potential getting better while valuations have moved to new lows. That is where we see the opportunity."
Why cheap is not enough
This is where Accendo's case parts company with a simple "buy the dip" theme.
"Short-term mood does not change what a company can become," Tavakka says. "It changes what you pay to own it. The work in between is ownership: the right board, the right management, focused strategy, disciplined capital allocation and enough patience for the company to become worth more."
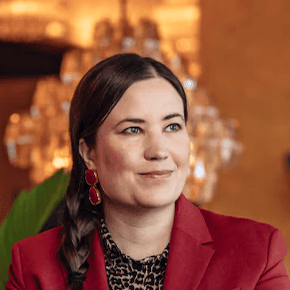
That is the part Accendo does itself. It runs a concentrated portfolio of Northern European small caps and works closely with boards, nomination committees and management teams rather than trading in and out. Tavakka was named Young Board Member of the Year at the 2025 Nordic Listed Leaders gala, recognition for that hands-on work.
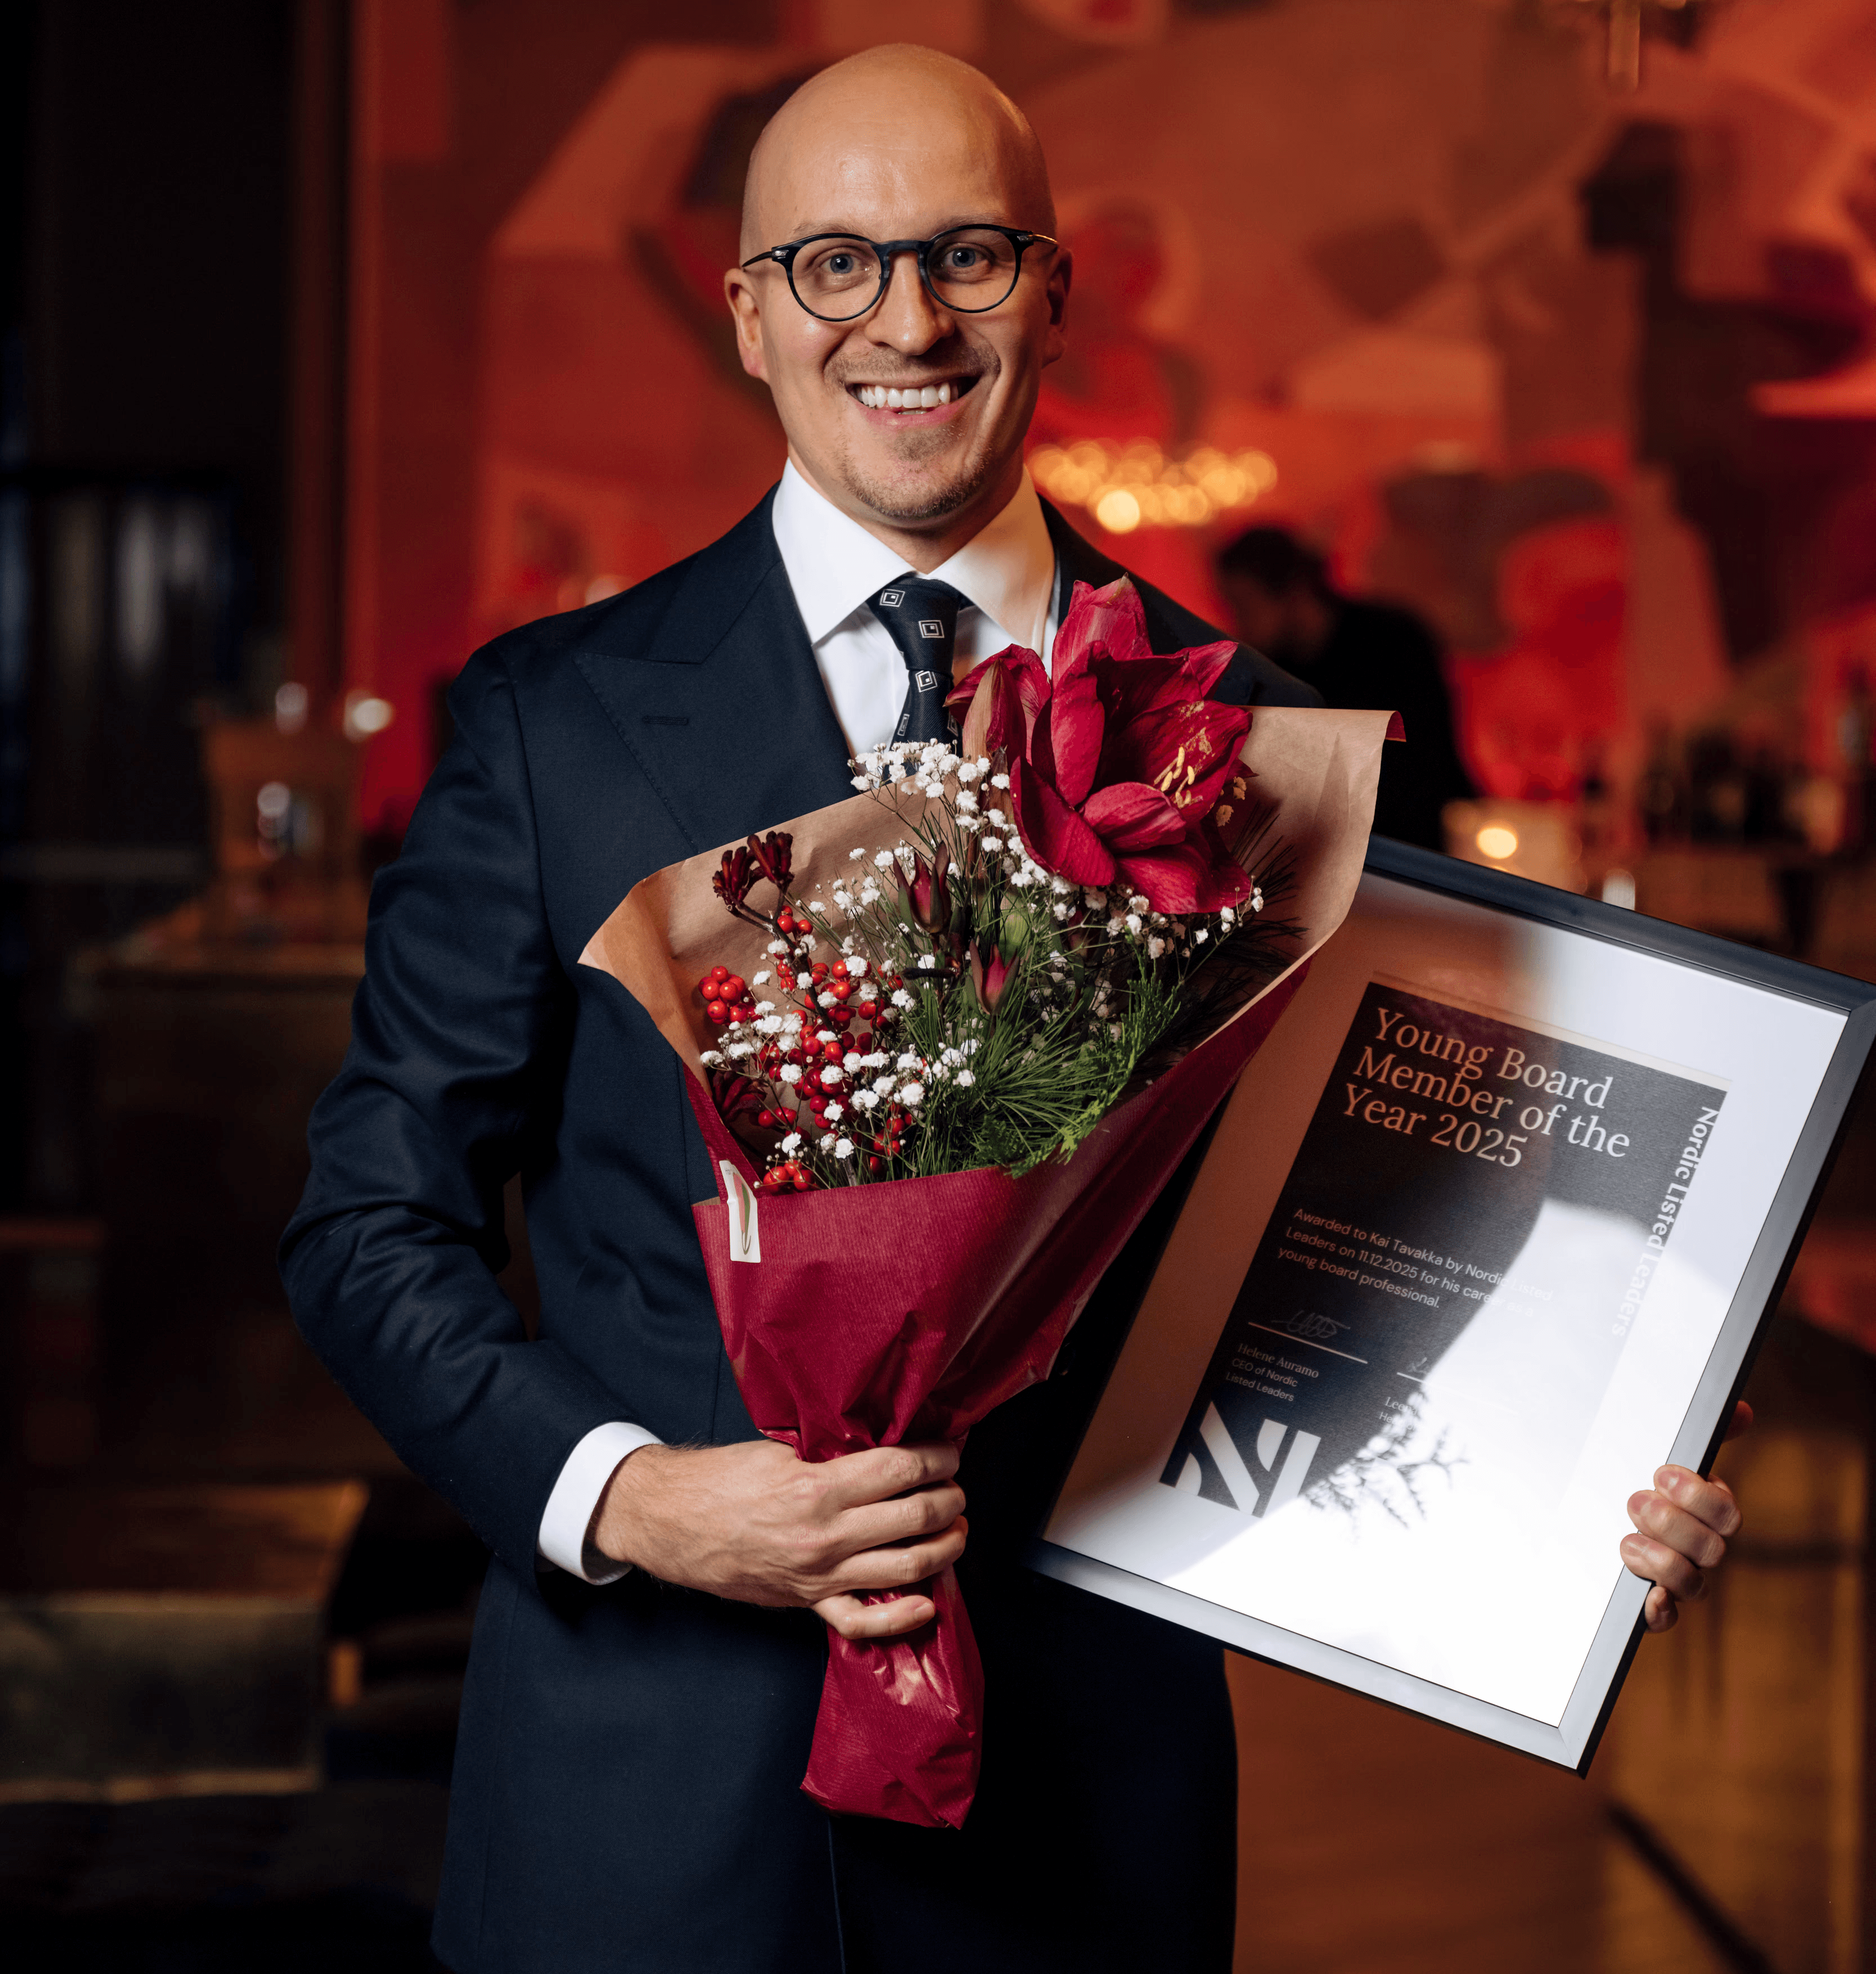
Kai Tavakka winning the award: Young Board Member of the Year at the 2025 Nordic Listed Leaders gala. Photographer: Eino Ansio. Nordic Listed Leaders is part of Listeds
The companies it has owned and engaged with as an active owner include Finnish cybersecurity firm SSH Communications Security and Helsinki-listed game studio Remedy Entertainment, alongside Swedish names such as the connectivity infrastructure group Hexatronic. On its own analysis, the entry point for the Nordic small- and micro-cap segment is among the most attractive it has seen in years.
The ownership gap
First North is, by Accendo’s description, largely a retail market, with private investors accounting for much of the trading. Today, those investors have access to a vast amount of information, but they complement rather than replace committed owners who work with the companies to strengthen strategy and governance.
Public small-cap markets, as Accendo frames it, need more committed, active and long-term owners. The market works best when it is not driven only by short-term traders or diversified portfolio managers, but also by owners willing to engage over several years. IPOs are one example. In Tavakka's view, the goal of an IPO should not be a strong first trading period. The more important question is whether the listing leaves the company with a better ownership structure: fresh capital, and owners with the incentive and the mandate to help in the next phase.
On our reading, the more useful lesson is not that First North is cheap. A two-thirds fall over five years establishes that on its own. It is that cheapness and a healthy market are not the same thing. A segment reprices back toward value only if someone is willing to own it through the doubt, and on First North that owner is often missing: the index has retail buyers and passive institutional money, but too few engaged, multi-year holders who take a board seat and stay.
Tavakka has a commercial interest in saying so; it is his company’s model. But the underlying point holds. A small-cap market can stay open and still be unhealthy: prices fall, good companies get sold too early or run out of steam, and the market grinds on. That is a governance problem before it is a pricing one, and it shows up in the ownership registers Listeds tracks company by company.
Accendo's model is typically a 10-30% stake and one or two board seats, including chair roles where it is needed. The work often includes recruiting board and management talent, focusing strategy, and strengthening financial and commercial discipline
Finland is one of the clearest cases. It has strong engineering and a deep research base, but has often struggled to turn that into global commercial winners before companies are sold or lose momentum.
Tavakka welcomes the region's new unicorns and venture capital success stories, but argues that Europe also needs healthier listed small-cap markets. These markets allow a wider range of investors to participate in the next generation of technology companies, and give companies another route to scale if the venture capital path has not yet produced success.
Where patience matters
The market still has not recovered, and Tavakka is careful not to call a bottom. Confidence may be improving, but that does not mean valuations turn immediately. A market down roughly 65% over five years is cheap, but not risk-free.
What Accendo offers is not a prediction of the turn but a way of operating through it: concentrated positions, long holding periods and active involvement in the companies it owns. Tavakka says this patient, active-ownership approach has helped Accendo outperform its equity benchmarks since its inception in 2008. For a private investor without that toolkit, the same entry point carries more timing risk.
"We do not pretend to know the exact bottom, and we are not too concerned about it," Tavakka says. "We buy quality we understand, help companies improve, and seek value-adding exits. That is our way to invest in this part of the market."
Accendo Capital is a Nordic active-ownership investor focused on listed small and micro-cap technology companies in Northern Europe. Founded in 2008, Accendo typically takes concentrated ownership positions and works with companies through boards, nomination committees and management teams over multi-year periods. Its current portfolio includes companies such as SSH Communications Security, Remedy Entertainment, Hexatronic Group, Impact Coatings, and Modelon.
·
5 min read
Explore and follow profiles from this article to get timely updates:

Weak consumer confidence has made First North small caps look cheap. Kai Tavakka of Accendo Capital argues the real constraint is ownership, not price. Small listed companies need committed, long-term owners who work with boards and management when the market is not paying attention.
First North has been a hard place to own. The Nasdaq First North Finland index is down about 29% over the past year and about 65% over the past five, as of 6 August 2026. For many investors, that is a reason to stay away. For Kai Tavakka, Managing Partner of the Nordic active-ownership investor Accendo Capital, it is closer to the opposite.
"The mistake is to read a falling small-cap index only as a verdict on the companies inside it," Tavakka says. "Often it is also a verdict on confidence, liquidity and who is willing to own these companies through the cycle."
Why the segment got cheaper
Accendo ties the sell-off to consumer confidence. Appetite for smaller, higher-risk listed companies tends to follow it, and on Accendo’s reading confidence in Finland and Sweden has stayed weak since 2021. When households feel poorer and investors become more cautious, money moves toward larger, more familiar names. In a retail-driven market, the buyers for small and micro caps can disappear quickly.
“That pulls valuations down across the small-cap segment,” Tavakka says, “even when the potential of selected companies has not deteriorated in the same way.”
The result, on Accendo's reading, is a market where price can detach from quality. Tavakka points to a sharp compression in valuation multiples over the past five years, even as many underlying companies have improved their products, technology and cost structures.
"Of course, several companies have not delivered on their original growth ambitions," he says. "But in selected cases, we see the potential getting better while valuations have moved to new lows. That is where we see the opportunity."
Why cheap is not enough
This is where Accendo's case parts company with a simple "buy the dip" theme.
"Short-term mood does not change what a company can become," Tavakka says. "It changes what you pay to own it. The work in between is ownership: the right board, the right management, focused strategy, disciplined capital allocation and enough patience for the company to become worth more."
That is the part Accendo does itself. It runs a concentrated portfolio of Northern European small caps and works closely with boards, nomination committees and management teams rather than trading in and out. Tavakka was named Young Board Member of the Year at the 2025 Nordic Listed Leaders gala, recognition for that hands-on work.
Kai Tavakka winning the award: Young Board Member of the Year at the 2025 Nordic Listed Leaders gala. Photographer: Eino Ansio. Nordic Listed Leaders is part of Listeds
The companies it has owned and engaged with as an active owner include Finnish cybersecurity firm SSH Communications Security and Helsinki-listed game studio Remedy Entertainment, alongside Swedish names such as the connectivity infrastructure group Hexatronic. On its own analysis, the entry point for the Nordic small- and micro-cap segment is among the most attractive it has seen in years.
The ownership gap
First North is, by Accendo’s description, largely a retail market, with private investors accounting for much of the trading. Today, those investors have access to a vast amount of information, but they complement rather than replace committed owners who work with the companies to strengthen strategy and governance.
Public small-cap markets, as Accendo frames it, need more committed, active and long-term owners. The market works best when it is not driven only by short-term traders or diversified portfolio managers, but also by owners willing to engage over several years. IPOs are one example. In Tavakka's view, the goal of an IPO should not be a strong first trading period. The more important question is whether the listing leaves the company with a better ownership structure: fresh capital, and owners with the incentive and the mandate to help in the next phase.
On our reading, the more useful lesson is not that First North is cheap. A two-thirds fall over five years establishes that on its own. It is that cheapness and a healthy market are not the same thing. A segment reprices back toward value only if someone is willing to own it through the doubt, and on First North that owner is often missing: the index has retail buyers and passive institutional money, but too few engaged, multi-year holders who take a board seat and stay.
Tavakka has a commercial interest in saying so; it is his company’s model. But the underlying point holds. A small-cap market can stay open and still be unhealthy: prices fall, good companies get sold too early or run out of steam, and the market grinds on. That is a governance problem before it is a pricing one, and it shows up in the ownership registers Listeds tracks company by company.
Accendo's model is typically a 10-30% stake and one or two board seats, including chair roles where it is needed. The work often includes recruiting board and management talent, focusing strategy, and strengthening financial and commercial discipline
Finland is one of the clearest cases. It has strong engineering and a deep research base, but has often struggled to turn that into global commercial winners before companies are sold or lose momentum.
Tavakka welcomes the region's new unicorns and venture capital success stories, but argues that Europe also needs healthier listed small-cap markets. These markets allow a wider range of investors to participate in the next generation of technology companies, and give companies another route to scale if the venture capital path has not yet produced success.
Where patience matters
The market still has not recovered, and Tavakka is careful not to call a bottom. Confidence may be improving, but that does not mean valuations turn immediately. A market down roughly 65% over five years is cheap, but not risk-free.
What Accendo offers is not a prediction of the turn but a way of operating through it: concentrated positions, long holding periods and active involvement in the companies it owns. Tavakka says this patient, active-ownership approach has helped Accendo outperform its equity benchmarks since its inception in 2008. For a private investor without that toolkit, the same entry point carries more timing risk.
"We do not pretend to know the exact bottom, and we are not too concerned about it," Tavakka says. "We buy quality we understand, help companies improve, and seek value-adding exits. That is our way to invest in this part of the market."
Accendo Capital is a Nordic active-ownership investor focused on listed small and micro-cap technology companies in Northern Europe. Founded in 2008, Accendo typically takes concentrated ownership positions and works with companies through boards, nomination committees and management teams over multi-year periods. Its current portfolio includes companies such as SSH Communications Security, Remedy Entertainment, Hexatronic Group, Impact Coatings, and Modelon.
Investor Event
Listeds Investor Event · Defence
Nordic defence is in a once-in-a-generation growth cycle. Eight listed and pre-IPO companies pitch to 100+ invited investors at Valkoinen Sali, Helsinki
21 September 2026

Latest on Listeds