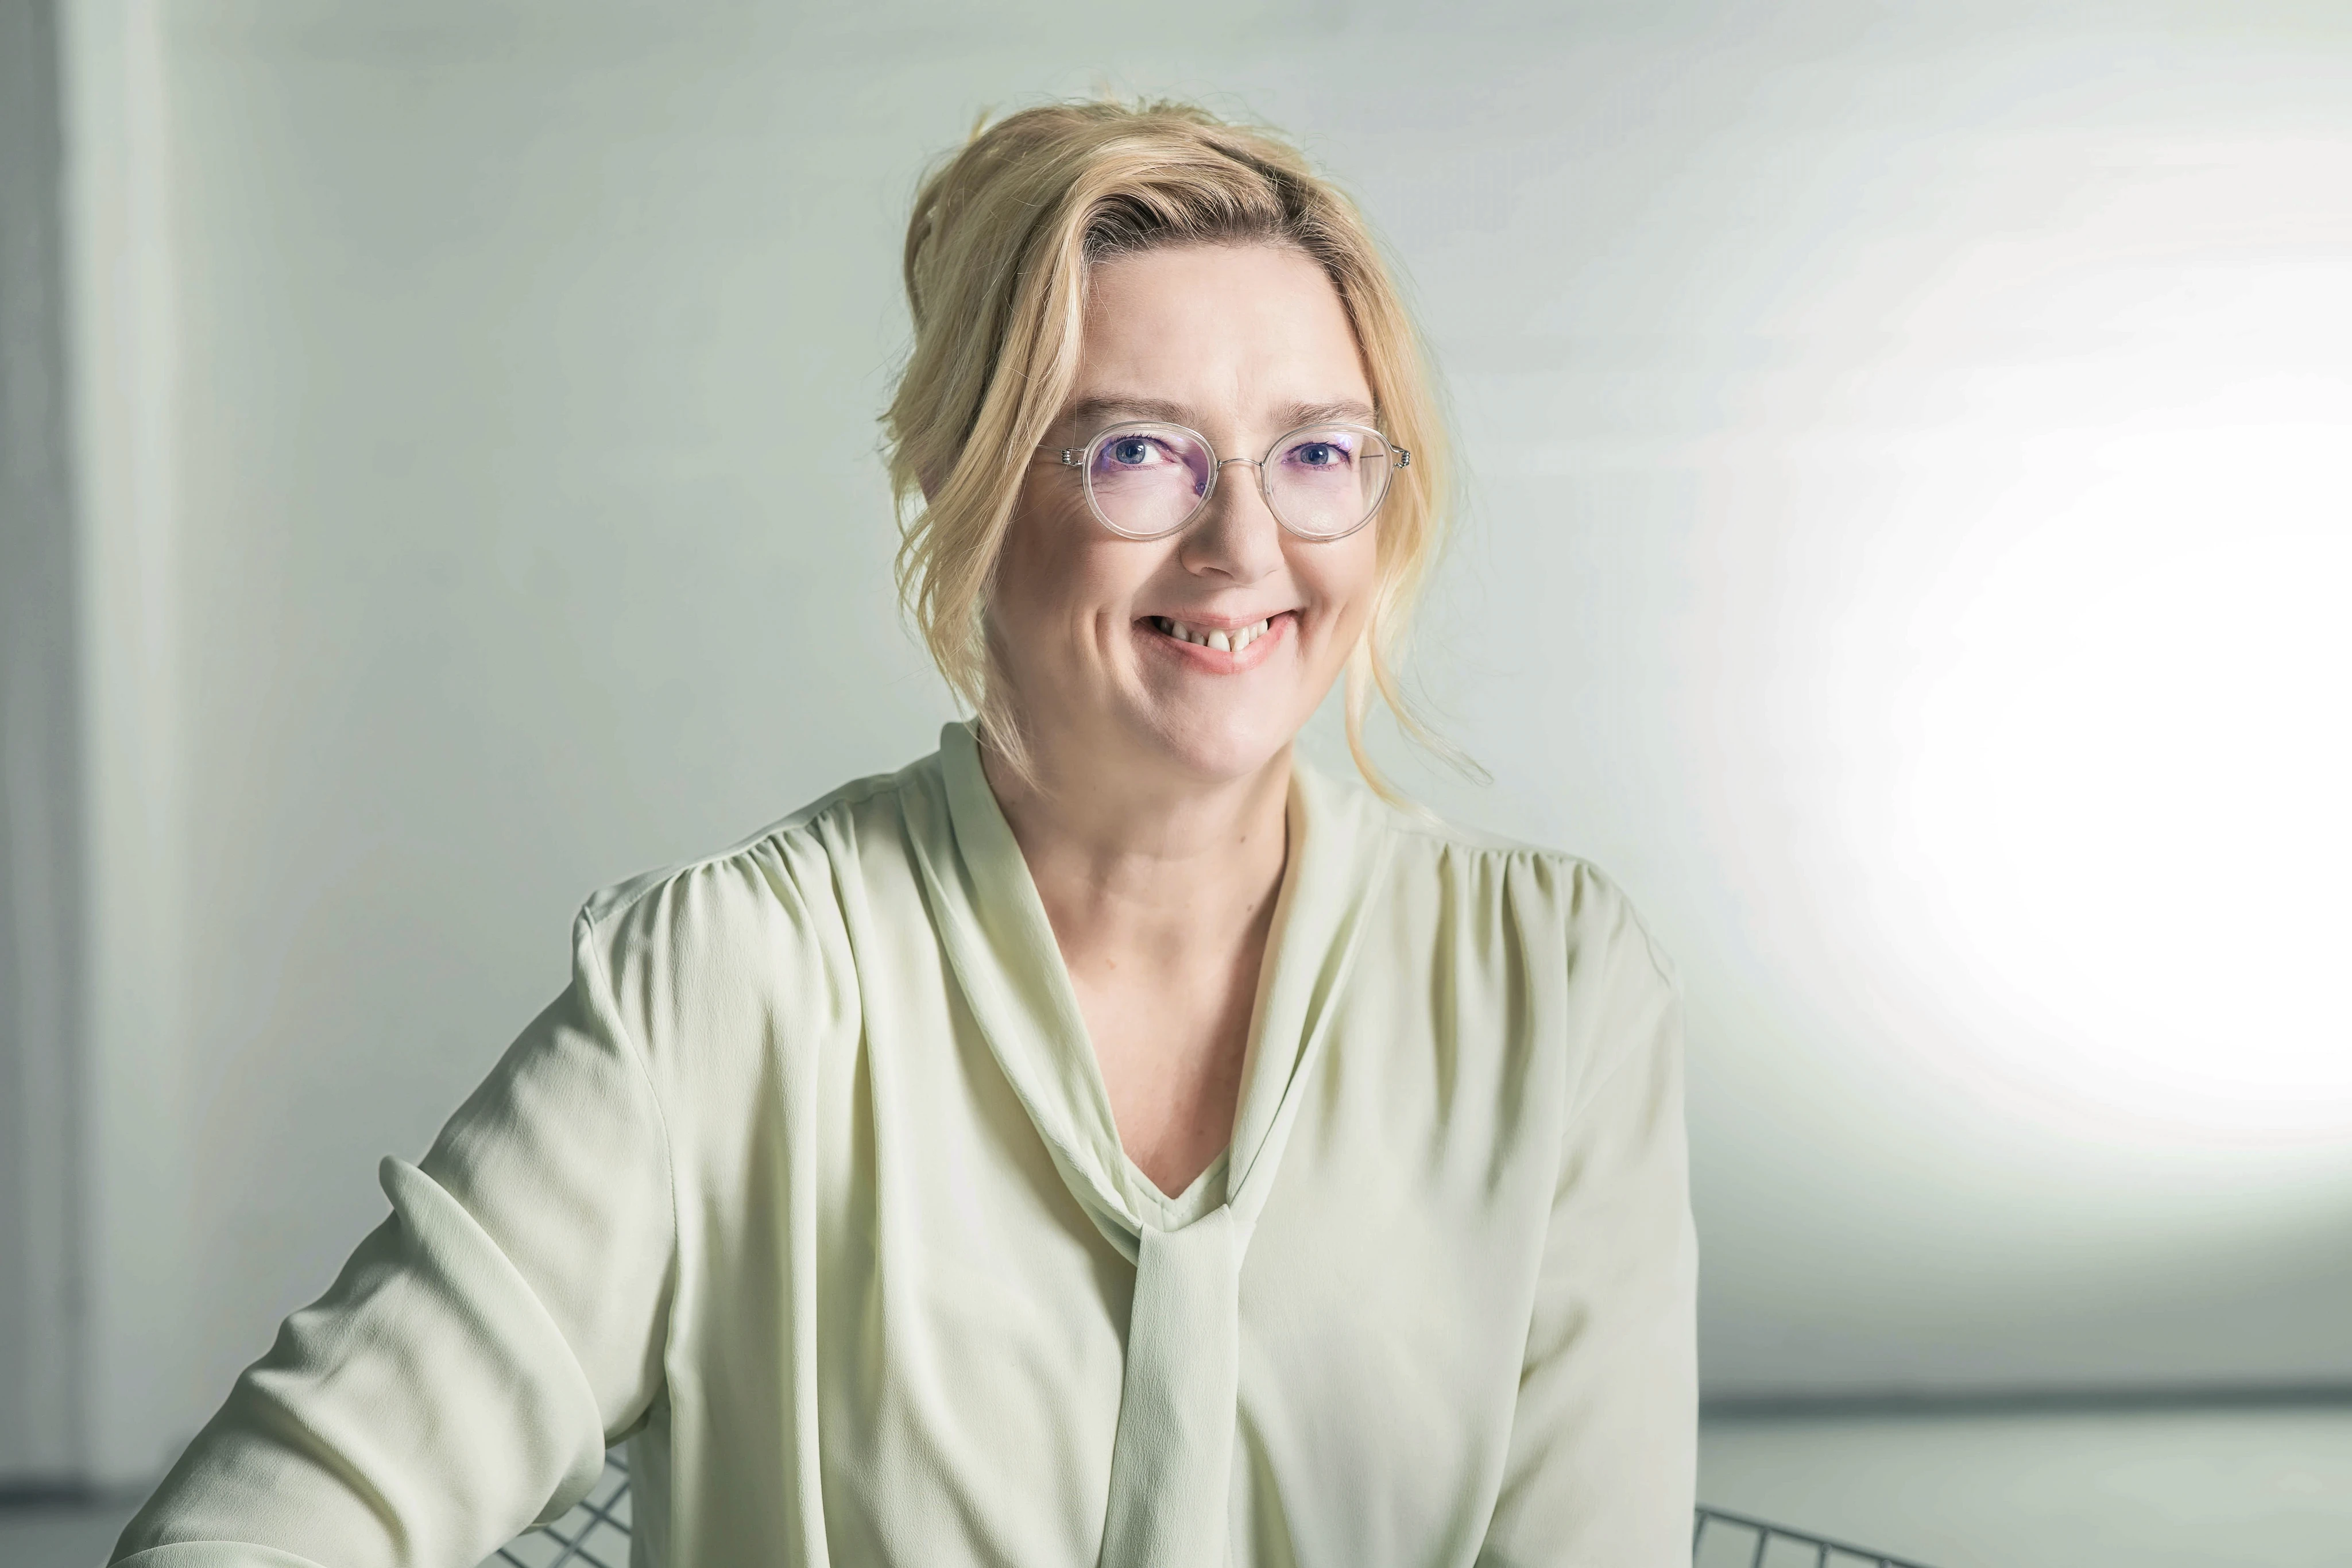
EU gender quotas regulating the composition of listed companies’ boards will enter into force this year. According to Emilia Kullas, attention should shift from the numbers to the underlying causes and structures.
As in other EU countries, a directive will come into force in Finland this year, introducing gender quotas for the boards of listed companies. The directive applies to all listed companies operating in the EU with more than 250 employees. In practice, the change means that at least 40 percent of non-executive board seats must be held by the underrepresented gender, as an NLL article points out.
Emilia Kullas, director of the Finnish Business and Policy Forum EVA (Elinkeinoelämän Valtuuskunta), argues that quotas may correct the numbers, but they cannot compensate for decades of narrow leadership pipelines and cultural assumptions about who belongs at the top.
“I’ve been critical towards the quotas because I think that the quotas don’t solve the Finnish structural problems,” Kullas says, adding that while quotas mandate outcomes, they do little to prepare candidates for board and governance roles.
Kullas has been leading EVA since 2019. EVA is a think tank that is funded by the Confederation of Finnish Industries (EK) and the Confederation of Finnish Industry and Employers (TT) Fund.
The numbers, at first glance, suggest steady progress. Across the EU, women hold 34 percent of board positions in the largest listed companies, unchanged from the previous year, according to the Gender Equality Index 2025. Finland’s score is 38 percent, whereas market leader France has 47 percent. France has had a law on gender quotas for the boards of large listed companies in place since 2011. The quotas have since been extended to also cover companies’ executive management teams.
Yet even in countries with long-standing quotas, the underlying talent structures have proved slow to change.
The pipeline narrows early
In Kullas’ view, the bottleneck sits much earlier and cuts both ways. Career choices in Finland remain highly gendered, and breaking that pattern requires change from individuals and institutions alike. It would be beneficial, she argues, for both men and women to choose a wider range of professional paths.
At the same time, companies themselves need to broaden their assumptions about what leadership potential looks like. Senior executives and nomination committees should consciously expand their recruitment lens instead of defaulting to familiar profiles.
“Diversity is well established in research as a source of organizational strength. Repeatedly selecting the same kind of candidate may feel safe, but it also limits perspective and reinforces the very pipelines that quotas are meant to correct.”
These structural constraints help explain why regulatory pressure is now being felt so acutely inside companies.
Boards feel the pressure
Inside Finnish companies, the upcoming rule update is already influencing behaviour, Kullas says.
“The effect has already been felt for at least a year. Especially on the smaller side, companies are scrambling to get new members to their boards who are not men.”
From a low starting point, progress can look dramatic. “At the beginning of the year 2000, if you took the 10 biggest listed companies in Finland, probably one or two had women on the board,” Kullas says. “The rest of them didn’t.”
Since then, representation has improved. But the pipeline feeding boards has remained selective. “Our path to the CEO position used to be very, very narrow,” she says. “And that hasn’t changed a lot in the bigger picture.”
Cultural norms are set long before board nominations
Part of the reason is education. “In our society, you end up being a CEO if you’re an engineer or if you have studied economics, especially finance,” Kullas says. “Studying marketing and ending up being a CEO of one of our biggest companies, it’s not possible if you’re a Finnish woman.”
These filters operate long before board nominations begin. Education choices, cultural expectations, and early career signalling narrow the field decades in advance. “In Finland, we have men’s careers, and we have women’s careers. We have very, very strict gender roles still. It starts so early, when kids are nine or 10 years old.”
By the time board nominations are discussed, the pool of candidates has already narrowed. “The quotas don’t fix that,” she says. Quotas do not change the process as they intervene only at the final stage.
Another constraint lies in how Finnish companies define board competence. “Owners tend to prioritize prior experience, and in Finland, this emphasis is particularly strong,” Kullas says, adding that as a result, the average age of board members remains high.
Few companies, especially large ones, treat board seats as an opportunity for structured sparring by deliberately bringing in younger individuals with different professional backgrounds. “This is a pity and a missed opportunity,” Kullas laments.
Why quotas still matter
Despite their limitations, Kullas is clear that quotas are not meaningless. “They are already having an effect,” she says.
“One good thing about quotas is that they force the nomination committees to make an effort,” Kullas says. “Very often you need to open up your eyes and start looking.”
Once that effort is made, change tends to accelerate. “Once you have one or two women board members, it’s much easier for the company to continue on that path,” she says.
Talent has never been the constraint
But does Finland have enough qualified talent?
“Absolutely. Of course, we have enough qualified women,” Kullas says, recalling some counterarguments. “That was the main explanation in the early 2000s. They said women are not interested, or that there’s nobody on this level. “They just didn’t see them.”
Still, for Kullas, quotas should remain a means, not an end. “A quota is a vehicle,” she says. “It shouldn’t be a goal in itself.”
Lasting success, in her view, would be visible far beyond board statistics. It would show up in broader educational paths to leadership, more women founding growth companies, and fewer assumptions about what a chief executive is expected to look like.
Whether the new rules coming into force next year will meaningfully bend Finland’s cultural norms remains an open question. Kullas is cautiously optimistic, noting that Finnish companies tend to take compliance seriously.
“Positive change is not only possible,” she says. “It’s also likely.”
About Emilia Kullas:
Emilia Kullas is a director of Finnish Business and Policy Forum EVA. She has broken the glass ceiling twice, becoming the first woman to lead EVA and the first woman to serve as editor-in-chief of the Finnish business weekly Talouselämä. She has written three books about investing for women together with Ninni Myllyoja.
·
5 min read
EU gender quotas regulating the composition of listed companies’ boards will enter into force this year. According to Emilia Kullas, attention should shift from the numbers to the underlying causes and structures.
As in other EU countries, a directive will come into force in Finland this year, introducing gender quotas for the boards of listed companies. The directive applies to all listed companies operating in the EU with more than 250 employees. In practice, the change means that at least 40 percent of non-executive board seats must be held by the underrepresented gender, as an NLL article points out.
Emilia Kullas, director of the Finnish Business and Policy Forum EVA (Elinkeinoelämän Valtuuskunta), argues that quotas may correct the numbers, but they cannot compensate for decades of narrow leadership pipelines and cultural assumptions about who belongs at the top.
“I’ve been critical towards the quotas because I think that the quotas don’t solve the Finnish structural problems,” Kullas says, adding that while quotas mandate outcomes, they do little to prepare candidates for board and governance roles.
Kullas has been leading EVA since 2019. EVA is a think tank that is funded by the Confederation of Finnish Industries (EK) and the Confederation of Finnish Industry and Employers (TT) Fund.
The numbers, at first glance, suggest steady progress. Across the EU, women hold 34 percent of board positions in the largest listed companies, unchanged from the previous year, according to the Gender Equality Index 2025. Finland’s score is 38 percent, whereas market leader France has 47 percent. France has had a law on gender quotas for the boards of large listed companies in place since 2011. The quotas have since been extended to also cover companies’ executive management teams.
Yet even in countries with long-standing quotas, the underlying talent structures have proved slow to change.
The pipeline narrows early
In Kullas’ view, the bottleneck sits much earlier and cuts both ways. Career choices in Finland remain highly gendered, and breaking that pattern requires change from individuals and institutions alike. It would be beneficial, she argues, for both men and women to choose a wider range of professional paths.
At the same time, companies themselves need to broaden their assumptions about what leadership potential looks like. Senior executives and nomination committees should consciously expand their recruitment lens instead of defaulting to familiar profiles.
“Diversity is well established in research as a source of organizational strength. Repeatedly selecting the same kind of candidate may feel safe, but it also limits perspective and reinforces the very pipelines that quotas are meant to correct.”
These structural constraints help explain why regulatory pressure is now being felt so acutely inside companies.
Boards feel the pressure
Inside Finnish companies, the upcoming rule update is already influencing behaviour, Kullas says.
“The effect has already been felt for at least a year. Especially on the smaller side, companies are scrambling to get new members to their boards who are not men.”
From a low starting point, progress can look dramatic. “At the beginning of the year 2000, if you took the 10 biggest listed companies in Finland, probably one or two had women on the board,” Kullas says. “The rest of them didn’t.”
Since then, representation has improved. But the pipeline feeding boards has remained selective. “Our path to the CEO position used to be very, very narrow,” she says. “And that hasn’t changed a lot in the bigger picture.”
Cultural norms are set long before board nominations
Part of the reason is education. “In our society, you end up being a CEO if you’re an engineer or if you have studied economics, especially finance,” Kullas says. “Studying marketing and ending up being a CEO of one of our biggest companies, it’s not possible if you’re a Finnish woman.”
These filters operate long before board nominations begin. Education choices, cultural expectations, and early career signalling narrow the field decades in advance. “In Finland, we have men’s careers, and we have women’s careers. We have very, very strict gender roles still. It starts so early, when kids are nine or 10 years old.”
By the time board nominations are discussed, the pool of candidates has already narrowed. “The quotas don’t fix that,” she says. Quotas do not change the process as they intervene only at the final stage.
Another constraint lies in how Finnish companies define board competence. “Owners tend to prioritize prior experience, and in Finland, this emphasis is particularly strong,” Kullas says, adding that as a result, the average age of board members remains high.
Few companies, especially large ones, treat board seats as an opportunity for structured sparring by deliberately bringing in younger individuals with different professional backgrounds. “This is a pity and a missed opportunity,” Kullas laments.
Why quotas still matter
Despite their limitations, Kullas is clear that quotas are not meaningless. “They are already having an effect,” she says.
“One good thing about quotas is that they force the nomination committees to make an effort,” Kullas says. “Very often you need to open up your eyes and start looking.”
Once that effort is made, change tends to accelerate. “Once you have one or two women board members, it’s much easier for the company to continue on that path,” she says.
Talent has never been the constraint
But does Finland have enough qualified talent?
“Absolutely. Of course, we have enough qualified women,” Kullas says, recalling some counterarguments. “That was the main explanation in the early 2000s. They said women are not interested, or that there’s nobody on this level. “They just didn’t see them.”
Still, for Kullas, quotas should remain a means, not an end. “A quota is a vehicle,” she says. “It shouldn’t be a goal in itself.”
Lasting success, in her view, would be visible far beyond board statistics. It would show up in broader educational paths to leadership, more women founding growth companies, and fewer assumptions about what a chief executive is expected to look like.
Whether the new rules coming into force next year will meaningfully bend Finland’s cultural norms remains an open question. Kullas is cautiously optimistic, noting that Finnish companies tend to take compliance seriously.
“Positive change is not only possible,” she says. “It’s also likely.”
About Emilia Kullas:
Emilia Kullas is a director of Finnish Business and Policy Forum EVA. She has broken the glass ceiling twice, becoming the first woman to lead EVA and the first woman to serve as editor-in-chief of the Finnish business weekly Talouselämä. She has written three books about investing for women together with Ninni Myllyoja.
Investor Event
Listeds Investor Event · Defence
Nordic defence is in a once-in-a-generation growth cycle. Eight listed and pre-IPO companies pitch to 100+ invited investors at Valkoinen Sali, Helsinki
21 September 2026

Latest on Listeds

